deNeergaard
Founder, The Loan Home Team · NMLS #2450179
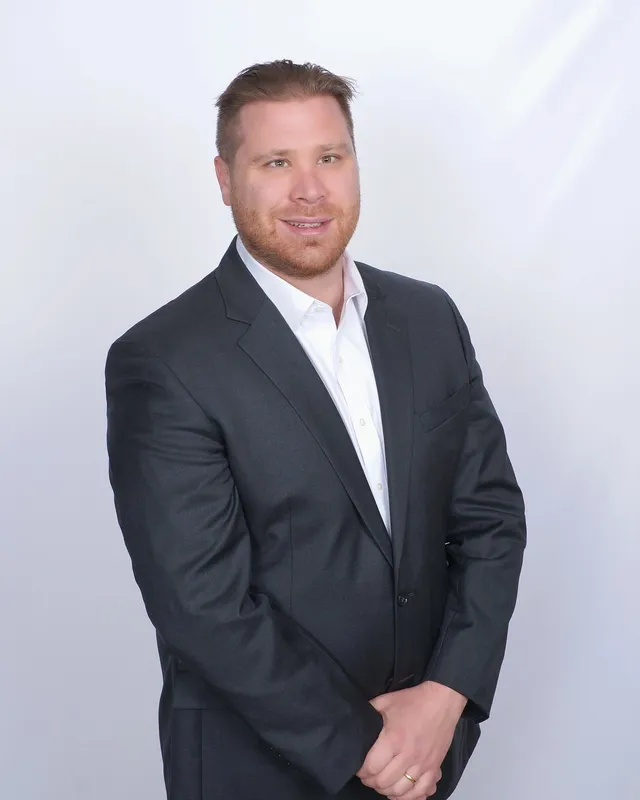
I’m Kevin deNeergaard, a mortgage loan originator (NMLS #2450179) with Scott Capital Group (NMLS #876527), licensed throughout New York State. Buying your first home with private down payment assistance, moving up, refinancing or growing an investment portfolio — I compare loan options from multiple lenders and guide you personally from the first call to the closing table, anywhere in Nassau and Suffolk County.
- 5.0 on Google · 30 reviews (Oct 2026)
- NMLS #2450179
- Scott Capital Group · Registered Mortgage Broker (NYS DFS)
- Equal Housing Opportunity
- Pre-approval: soft credit check, no effect on your score
Every move starts with
the right loan.
Tell me where you're headed. I'll match you with the programs that fit and walk you through each step.
Buy a Home
Pre-approval support, first-time buyer programs, private down payment assistance and low down payment options, so your offer is ready when the right house is.
Get StartedRefinance
Review your current mortgage to see whether a different rate, a shorter term or a cash-out refinance makes sense for your goals.
Get StartedInvest
Loans for 1–4 family and commercial properties, plus fix-and-flip financing. I started my own career as a real estate investor.
Get Started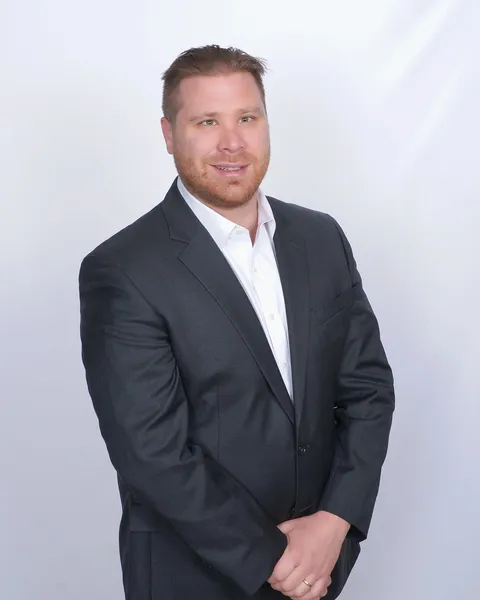
An investor's eye.
A borrower's advocate.
I began my real estate career as an investor and soon found my real passion in mortgage financing. With more than a decade in real estate and mortgages, I know both the fine print of mortgage products and the full scope of a real estate transaction.
Having been through it myself, I understand what borrowers face — and I'm committed to guiding you through every step, with your goals first.
— Kevin deNeergaard, Founder, The Loan Home Team
Local, personal and on your side.
As featured in
My work as a Long Island real estate investor and owner has drawn coverage from the regional business press.
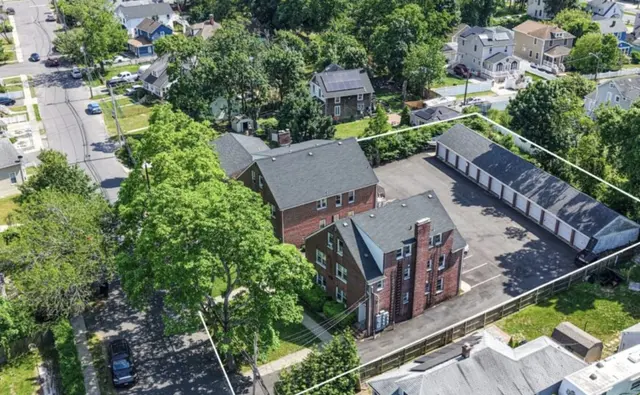 LONG ISLAND BUSINESS NEWS
September 9, 2026
Bay Shore multifamily fetches $3.4M in off-market deal
Read the Article
Coverage relates to my separate real estate investment and management business, which is not part of The Loan Home Team or Scott Capital Group's mortgage services.
Solutions for nearly
every scenario.
I compare loan programs from multiple lenders to find the right fit for your purchase, refinance or investment.
Home Purchase
Financing for single-family homes, condos and multi-family properties.
02Refinance
Rate-and-term and cash-out refinance options.
03Conventional & Jumbo
Conforming, high-balance and jumbo financing for primary homes, second homes and investment property.
04FHA Loans
Government-backed loans with flexible credit and down payment requirements.
05VA Loans
For eligible veterans, active-duty service members and eligible surviving spouses.
06First-Time Buyers
Programs and step-by-step guidance for first-time homebuyers.
07Down Payment Assistance
Private programs available through lenders I work with — not state or county programs — that may reduce the cash you need to buy.
08DSCR Loans
Rental loans that qualify on the property’s rent, not your tax returns.
09Investment Property
1–4 family rentals, mixed-use, commercial and fix-and-flip financing.
10Bridge Loans
Short-term financing to help you buy before you sell.
11Reverse Mortgages
Long Island and NYC options for eligible homeowners age 62 and older.
12Low Credit Score
Options when your credit score is low or you’re rebuilding.
All loans are subject to credit approval, property approval and underwriting guidelines. Down payment assistance refers to private programs available through lenders I work with, not state, county or other government programs. Terms, eligibility and availability vary by program and lender, are subject to underwriting, and can change or end without notice. Not all applicants will qualify.
See all loan programsEvery step, from first call to keys.
You deal with me at every stage. Here is exactly how a purchase runs, and what I handle at each point.
Consultation
We talk through your goals, budget and timeline, and I tell you what you can realistically buy.
Pre-Approval
I review your credit, income and assets, then issue a pre-approval letter you can attach to an offer. This step takes only a soft credit check, so it won’t affect your credit score.
House Hunting
Found the house? I run the exact numbers on that property and update your letter for the offer price, often the same day.
Application
You complete one secure application and upload your documents once. I build the file around your situation.
Processing
The lender orders the appraisal, and I coordinate title, insurance, your attorney and your agent so nothing waits on paperwork.
Underwriting
Your file goes into underwriting for review. I answer every question and clear conditions fast to protect your closing date.
Clear To Close
Final figures are confirmed, you review your Closing Disclosure, and we lock in the closing date.
Closing Day
You sign, you get the keys, and I'm still a phone call away for whatever comes next.
I shop your mortgage with multiple lenders, Nassau to Montauk
I help buyers and homeowners across Nassau and Suffolk County. Choose your county for its loan limits, property tax rules and local details.
Nassau County mortgages
The towns of Hempstead, North Hempstead and Oyster Bay, plus the cities of Glen Cove and Long Beach: 2026 loan limits, county assessments, ARC grievances and STAR.
Nassau County mortgage guideSuffolk County mortgages
All ten towns, from Babylon and Huntington to Brookhaven and the North and South Forks: town assessors, Grievance Day, flood zones and East End rental rules.
Suffolk County mortgage guideEstimate your
monthly payment.
With a smaller down payment, mortgage insurance is usually required and isn't included above.
For illustration only. This is not a loan offer, rate quote or commitment to lend. The payment uses the rate you enter. Your actual rate and payment depend on credit, property, loan program and market conditions, and may not include mortgage insurance, HOA dues or other costs.
Long Island Mortgages with
Kevin
deNeergaard
- 5.0 on Google · 30 reviews (Oct 2026)
- NMLS #2450179
- Scott Capital Group · Registered Mortgage Broker (NYS DFS)
- Equal Housing Opportunity
- Pre-approval: soft credit check, no effect on your score
Founder, The Loan Home Team · NMLS #2450179
I’m Kevin deNeergaard, a mortgage loan originator (NMLS #2450179) with Scott Capital Group (NMLS #876527), licensed throughout New York State. Buying your first home with private down payment assistance, moving up, refinancing or growing an investment portfolio — I compare loan options from multiple lenders and guide you from the first call to closing, anywhere in Nassau and Suffolk County.
Every move starts with the right loan.
An investor's eye. A borrower's advocate.
I began my real estate career as an investor and found my real passion in mortgage financing. With more than a decade in real estate and mortgages, I know both the fine print of mortgage products and the full scope of a transaction.
I'm committed to guiding you through every step, with your goals first.
Call 631-250-6930Local, personal and on your side.
As featured in
My work as a Long Island real estate investor and owner has drawn coverage from the regional business press.
LONG ISLAND BUSINESS NEWS
September 9, 2026
Bay Shore multifamily fetches $3.4M in off-market deal
Read the Article
Coverage relates to my separate real estate investment and management business, which is not part of The Loan Home Team or Scott Capital Group's mortgage services.
Solutions for nearly every scenario.
Home Purchase
Single-family, condo & multi-family.Refinance
Rate-and-term and cash-out.Conventional & Jumbo
Conforming, high-balance & jumbo.FHA Loans
Flexible credit & down payment rules.VA Loans
For eligible veterans & service members.First-Time Buyers
Programs and guidance.Down Payment Assistance
Private programs through lenders I work with — not state or county.DSCR Loans
Qualify on the rent, not tax returns.Investment Property
Rentals, commercial & flips.Bridge Loans
Buy before you sell.Reverse Mortgages
For eligible homeowners 62+.Low Credit Score
Options with a lower credit score.All loans are subject to credit approval, property approval and underwriting guidelines. Down payment assistance refers to private programs available through lenders I work with, not state, county or other government programs. Terms, eligibility and availability vary by program and lender, are subject to underwriting, and can change or end without notice. Not all applicants will qualify.
See all loan programsEvery step, from first call to keys.
You deal with me at every stage. Here is how a purchase actually runs.
I shop your mortgage with multiple lenders, Nassau to Montauk
I help buyers and homeowners across Nassau and Suffolk County. Choose your county for its loan limits, property tax rules and local details.
Nassau County mortgages
The towns of Hempstead, North Hempstead and Oyster Bay, plus the cities of Glen Cove and Long Beach: 2026 loan limits, county assessments, ARC grievances and STAR.
Nassau County mortgage guideSuffolk County mortgages
All ten towns, from Babylon and Huntington to Brookhaven and the North and South Forks: town assessors, Grievance Day, flood zones and East End rental rules.
Suffolk County mortgage guideEstimate your monthly payment.
With a smaller down payment, mortgage insurance is usually required and isn't included.
For illustration only. Not a loan offer, rate quote or commitment to lend. The payment uses the rate you enter. Actual rate and payment depend on credit, property, program and market conditions.
What my clients say.
Every review below was left by a client on Google, unedited.
Rated 5.0 on Google · 5.0 on Zillow
As first-time home buyers, we couldn't have asked for a better loan officer. Kevin made the entire process feel smooth and manageable, always taking the time to explain everything clearly and answer all our questions. My husband and I felt supported and informed every step of the way. Highly recommend!
Kevin was extremely communicative. There was not one step of the process that I didn’t know what was going on. Explained everything in detail and jumped through quite a few hoops to make our family’s dream come true.
This process was so easy thanks to Kevin and Nicole. Appreciated how quickly all our questions were answered and how thoroughly everything was explained.
Reviews come from our Google Business Profile. Leave one here.
From the Long Island mortgage blog
Mortgage Recast on Long Island
Put a lump sum toward your loan, keep your rate and lower your payment. What it costs, how it compares with a refinance, and a calculator. Homeowners · 7 min readCash-Out Refinance on Long Island
Turn part of your home’s equity into cash. How much you could take out, what it costs, and a calculator. Market Data · Updated monthlyLong Island Housing Market: Nassau and Suffolk Prices
Nassau and Suffolk single-family medians, month by month, per OneKey MLS, and what they mean for the size of the loan you’ll need.Questions? Ask me anything.
Loan options, timing or the process itself — reach out anytime.
631-250-6930How do I know how much I can borrow?
It depends on your income, monthly debts, credit, savings and the loan program, and on Long Island the property tax bill is a big part of the payment a lender counts. My calculator shows how much house you can afford on Long Island at a comfortable and a stretch price, and I can check those numbers with you before you start shopping.
What documents do I need to apply?
Typically proof of income, tax returns, bank statements, identification and information about your debts and assets. I will tell you exactly what your application requires. My mortgage document checklist builds a printable list for your situation, with the reason for each item.
How long does the process take?
Most loans take about 30 to 45 days from application to closing. Some close in as little as two to three weeks when documents come in promptly and there are no appraisal, title or underwriting delays. Refinancing? My refinance timeline walks through each step, from application to your first new payment.
Do you offer down payment assistance?
Yes. Private down payment assistance programs are available through lenders I work with, and I can pair one with your loan. They are not New York State, county or town programs and are not affiliated with or endorsed by any government agency. Terms, eligibility and availability vary by program and lender, are subject to credit, income, property and underwriting guidelines, and can change or end without notice. Not everyone will qualify.
Can I get pre-approved before I find a house?
Yes, and you should. A pre-approval tells you your price range and shows sellers you are ready to perform. It takes a short application and a few documents, and I can often turn it around the same day.
Will getting pre-approved hurt my credit score?
No. Pre-approval takes only a soft credit check, so it won’t affect your credit score. A hard credit inquiry comes later, only when you’re ready to move forward with a loan and you authorize it.
What do you do that a bank doesn't?
A bank offers its own loans. I compare programs from the lenders I work with; the lender you choose approves, underwrites and funds the loan, and I stay your point of contact through closing.
Do you only work with Long Island buyers?
Most of my clients are on Long Island, and I’m licensed throughout New York State. See my Nassau County mortgage broker guide and Suffolk County mortgage broker guide. Buying or refinancing outside New York? Ask me. Depending on the state, I may be able to help.
Let's talk about
your next move.
Get a personalized quote, a second look at an offer you've received, or a straight answer to a quick question. I'll get back to you personally.
Pre-approval takes only a soft credit check, so it won’t affect your credit score.
- 5.0 on Google · 30 reviews (Oct 2026)
- NMLS #2450179
- Scott Capital Group · Registered Mortgage Broker (NYS DFS)
- Equal Housing Opportunity
Request a personalized quote
Consent to messages is not a condition of any purchase or loan. See the Privacy Policy and Terms of Service.
From the Long Island mortgage blog
Homeowners · 6 min readMortgage Recast on Long Island
Put a lump sum toward your loan, keep your rate and lower your payment. What it costs, how it compares with a refinance, and a calculator. Homeowners · 7 min readCash-Out Refinance on Long Island
Turn part of your home’s equity into cash. How much you could take out, what it costs, and a calculator. Market Data · Updated monthlyLong Island Housing Market: Nassau and Suffolk Prices
Nassau and Suffolk single-family medians, month by month, per OneKey MLS, and what they mean for the size of the loan you’ll need. See all articlesAsk me anything.
How do I know how much I can borrow?
It depends on your income, monthly debts, credit, savings and the loan program, and on Long Island the property tax bill is a big part of the payment a lender counts. My calculator shows how much house you can afford on Long Island at a comfortable and a stretch price, and I can check those numbers with you before you start shopping.
What documents do I need to apply?
Typically proof of income, tax returns, bank statements, identification and information about your debts and assets. I will tell you exactly what your application requires. My mortgage document checklist builds a printable list for your situation, with the reason for each item.
How long does the process take?
Most loans take about 30 to 45 days from application to closing. Some close in as little as two to three weeks when documents come in promptly and there are no appraisal, title or underwriting delays. Refinancing? My refinance timeline walks through each step, from application to your first new payment.
Do you offer down payment assistance?
Yes. Private down payment assistance programs are available through lenders I work with, and I can pair one with your loan. They are not New York State, county or town programs and are not affiliated with or endorsed by any government agency. Terms, eligibility and availability vary by program and lender, are subject to credit, income, property and underwriting guidelines, and can change or end without notice. Not everyone will qualify.
Can I get pre-approved before I find a house?
Yes, and you should. A pre-approval tells you your price range and shows sellers you are ready to perform. It takes a short application and a few documents, and I can often turn it around the same day.
Will getting pre-approved hurt my credit score?
No. Pre-approval takes only a soft credit check, so it won’t affect your credit score. A hard credit inquiry comes later, only when you’re ready to move forward with a loan and you authorize it.
What do you do that a bank doesn't?
A bank offers its own loans. I compare programs from the lenders I work with; the lender you choose approves, underwrites and funds the loan, and I stay your point of contact through closing.
Do you only work with Long Island buyers?
Most of my clients are on Long Island, and I’m licensed throughout New York State. See my Nassau County mortgage broker guide and Suffolk County mortgage broker guide. Buying or refinancing outside New York? Ask me. Depending on the state, I may be able to help.
Let's talk about your next move.
Pre-approval takes only a soft credit check, so it won’t affect your credit score.
Call 631-250-6930- 5.0 on Google · 30 reviews (Oct 2026)
- NMLS #2450179
- Scott Capital Group · Registered Mortgage Broker (NYS DFS)
- Equal Housing Opportunity
Consent to messages is not a condition of any purchase or loan.